Coverage Options
Every piece of an auto policy on its own, with the ceiling it comes with and the ground it leaves bare.
Break A Policy Apart And It Makes Sense
Damage You Cause Others
This is the piece that pays when you dent someone else, their car or their fence while you are behind the wheel. It sits underneath every other choice on your policy and it is the part the state actually requires of you.
The number you pick here matters far more than most drivers guess. One tap in traffic can turn into body work, a rental and an injury claim, and a thin limit is gone by the time all three arrive.
Tell me your weekly mileage and the roads you usually take, and I size this layer to match.
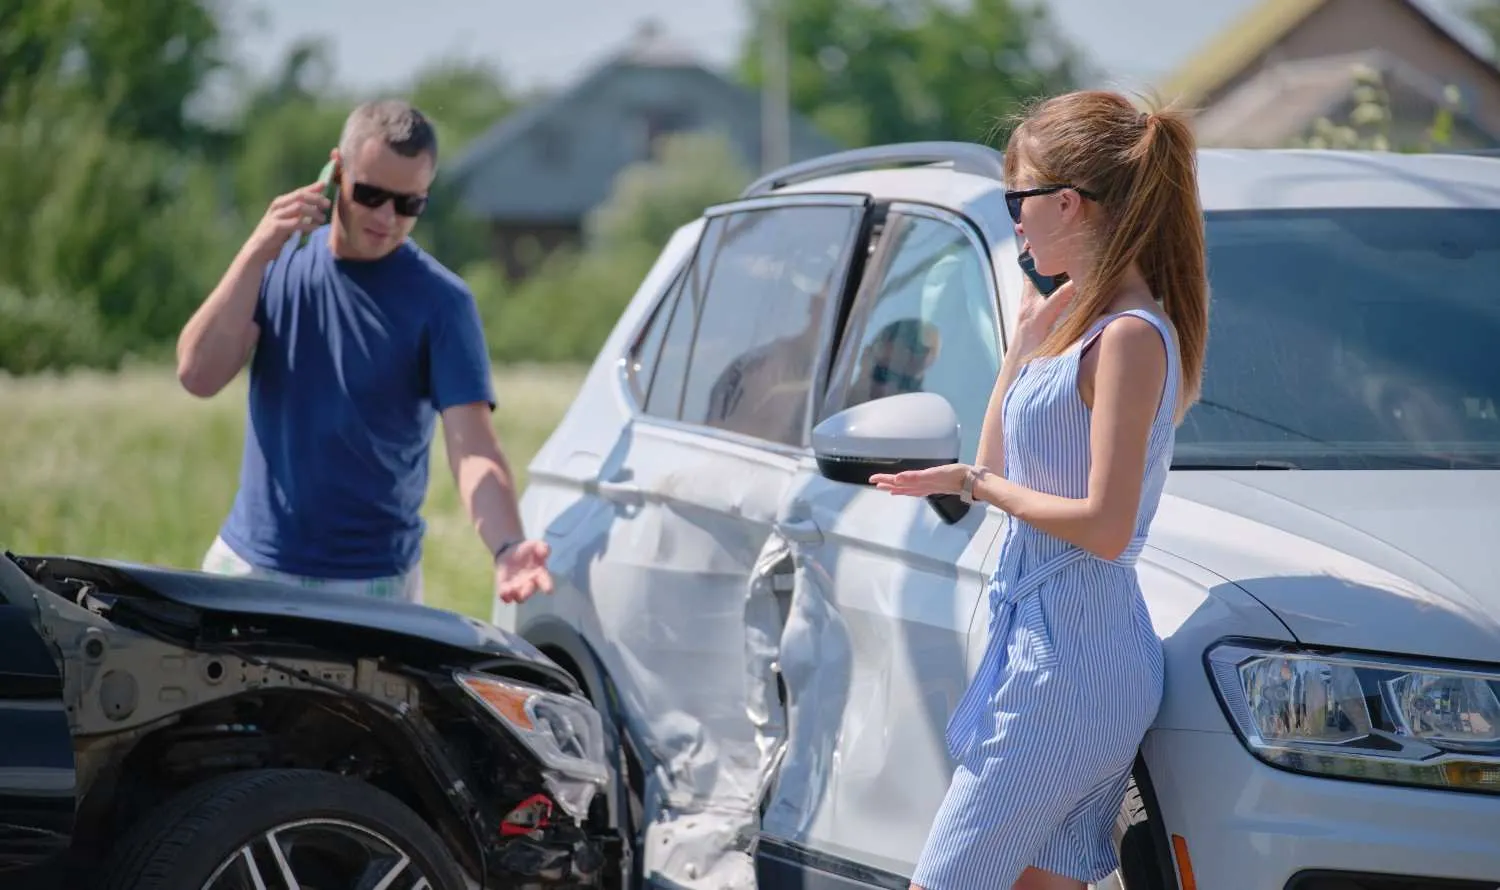
When A Crash Happens
A collision leaves you with far more than a bent panel. There is a shop bill waiting, a car you cannot drive, paperwork stacking up and an argument about who pays for all of it. This is the piece I build to carry that load.
Choices here run from paying for your own car no matter who was at fault, out to covering a rental while the shop has yours. Each one moves the price, so I quote them one at a time instead of hiding them in a single figure.
I state your deductible early, because that figure decides what a minor claim truly costs you.
More Names And More Cars
Putting a spouse, a teenager or a second car on a policy shifts it more than most people expect. Age, driving record and how often each person takes the wheel all tug the price in different directions.
I quote every addition before it goes on, with the change to your total shown in plain figures. Then your household can decide whether to name someone, keep the cars on separate policies or bring them under one.
Listing an occasional driver honestly protects your claim later, so a guess here never pays for itself.
Extras That Earn Their Keep
Right for some drivers, wasted on othersRoadside Help
Cover for the day your car quits far from your driveway, including a tow to a shop. It pays off on a long commute or an aging car, and does little when you rarely leave your own neighborhood.
Uninsured Driver Cover
Pays for the damage when the person who hit you carries no policy at all. It fills the hole where the other side cannot pay, which is the worst spot after a crash you did not cause.
Windshield And Window Glass
A stone chip or a spreading crack is among the most routine repairs there is. Glass cover carries a deductible of its own, so read that line before you assume the fix costs nothing.
Belongings Left In The Car
Drivers often assume a laptop or a stroller in the back seat is already covered when it is not. Where this does exist, the cap is usually small, so read the limit rather than the headline.
A Car While Yours Waits
Keeps you on the road while your own car sits in a repair bay. Its worth comes down to whether your week survives without a set of keys.
Legal Cost Cover
Pays the bills when a road claim ends up needing a lawyer on either side. It is quiet cover that only proves itself when an argument over fault will not settle.
How Getting Covered Works
Send the car details
Year, model and how it gets used, plus who else drives it. It takes about two minutes.
Look through the options
What each one covers sits next to what it leaves out, so you can line them up fairly.
Pick the one that fits
It gets set up from there and I stay with it right up until the cover is running.